Entertainment Overview
University funds may be used for allowable business meetings, entertainment, programmatic activities, and other official occasions when the expense has a clear University business purpose, is reasonable and cost-effective, uses an allowable funding source, and meets applicable documentation and approval requirements.
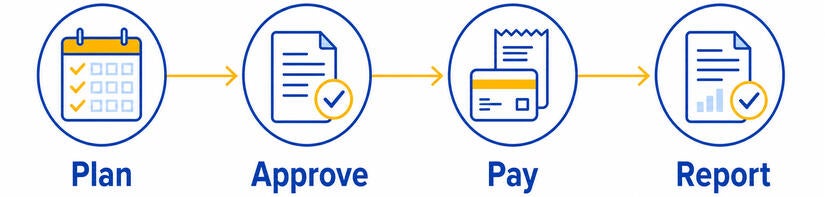
Before committing University funds
Confirm that the expense:
- Has a clear and necessary University business purpose.
- Is reasonable and appropriate for the occasion.
- Uses an allowable funding source with sufficient available funds.
- Is the most appropriate option after considering equally effective alternatives.
- Includes an official host or designated University representative when required.
- Meets the applicable per-person limit.
- Uses an allowable payment or purchasing method.
- Can be supported with the required documentation and approvals.
Choose the guidance you need
| Question | Use this page |
|---|---|
| Is food appropriate for this working session? | Business Meetings |
| Who must attend and serve as the official host? | Hosting & Official Functions |
| Do the attendees or occasion change the requirements? | Employee vs. Non-Employee Entertainment |
| Can alcohol be purchased, and which funds may be used? | Alcohol Policy |
| What receipts and event information must be retained? | Required Documentation & Receipts |
| Is additional or exceptional approval required? | Approval Requirements |
Current per-person limits
Effective for events occurring on or after September 1, 2025, the following BUS-79 maximums apply unless UCR or the applicable funding source establishes a lower limit. The per-person amount includes food, beverages, labor, sales tax, delivery, gratuity, service charges, and other meal-related service fees.
Facility rental, equipment rental, decorations, and similar non-meal costs may be excluded from the calculation when separately stated. Excluding an expense from the calculation does not make it automatically allowable.
| Breakfast | Lunch | Dinner | Light refreshments |
|---|---|---|---|
| $34 | $59 | $103 | $24 |
Choose an appropriate payment method
Review the Payment Card & Restricted Items Matrix before making a purchase. The payment method does not determine whether an expense is allowable. An expense paid with a University card must still meet all business-purpose, funding, approval, and documentation requirements.
| Expense | T&E Card | PCard | What to know |
|---|---|---|---|
| Business meal | Allowed | Not allowed | The expense must meet BUS-79 requirements and use an allowable funding source. |
| Catering or business-meeting venue rental | Allowed with conditions | Not allowed | Contracts and venue agreements require Procurement Services review before commitment. Events exceeding $5,000 or requiring a contract must use a purchase order. |
| Social meal or entertainment event | Allowed with conditions | Not allowed | Apply BUS-79, funding, approval, alcohol, and documentation requirements. |
| Entertainment contract, such as a band or theater group | Not allowed | Not allowed | Route the agreement to Procurement Services and use a purchase order. |
| Equipment rental, flowers, or similar event items | Not allowed | Review the matrix | Use the purchasing method identified in the matrix. Event-specific decorations may require a purchase order or restricted PCard process. |
| Employee or nonemployee gift or prize | Not allowed | Generally not allowed | Follow the UCR gift guide. Limited PCard exceptions apply only through authorized programs or with Procurement Services approval. |
Expenses that are not allowable
University funds may not be used for:
- Lavish or extravagant entertainment.
- Personal purchases or expenses without a University business purpose.
- Monetary contributions to a political campaign or candidate.
- Employee birthdays, weddings, anniversaries, or ordinary farewell gatherings.
- Expenses prohibited by a State, federal, sponsored, gift, donor-restricted, or other restricted funding source.
- Expenses that are unsupported, insufficiently documented, or improperly approved.
Related resources
Overview questions
-
Could the expense become taxable?
A meal or entertainment expense may be treated as taxable income when it is not directly related to the employee’s job, is lavish or extravagant, lacks adequate documentation, or occurs without the official host or another designated University representative when attendance is required.
-
What is a programmatic activity?
A programmatic activity directly supports the University’s mission, such as student enrichment, training, recruitment, or community engagement. Document the program purpose, participants, and how the expense supports the activity.
-
What about gifts, awards, or prizes?
Gifts and awards provided to employees or nonemployees must have an allowable University business purpose and comply with applicable limits, approval, tax-reporting, and payment-method requirements.
Before purchasing or reimbursing a gift or award, review the Reference Guide on Giving Gifts to Employees/Non-Employees.